Residential Mortgages
Access the whole of the UK's panel of lenders. We align you to the best product for your individual circumstances.
Did you know most families are one crisis away from financial hardship? Unfortunately, there are some devastating numbers out there. A parent of children under 18 dies every 20 minutes in the UK, equating to around 127 children newly bereaved of a parent every day. We couldn’t believe these statistics, and we just wish it wasn’t true. But equally, every day on Britain’s roads, more than 80 people are seriously injured. And sadly, more than 403,000 people in the UK are now diagnosed with cancer each year; the highest number on record. We are not trying to scare you. But in our line of work, it’s our job to protect you and make sure your family and livelihood are looked after.
Research published in 2026 by CIExpert, the most comprehensive study of its kind, drawing on the views of 10,000 consumers, found that around seven in ten people had seen or heard nothing about Income Protection in the past year. The same proportion had had no exposure to Critical Illness Cover. This represents an enormous protection gap, and it has barely moved since the equivalent study in 2024.
Life Insurance, Critical Illness Cover, and Income Protection are three distinct but complementary products and understanding how they work together is key to building a robust financial safety net.
Life insurance pays a tax-free lump sum to your family if you die during the term of the policy. It is the cornerstone of financial protection. It ensures that a mortgage can be repaid, debts can be cleared, and your family’s standard of living can be maintained. Critical Illness Cover pays a tax-free lump sum if you are diagnosed with a serious condition such as cancer, heart attack or stroke. Policies typically cover 40–50 listed conditions. Income Protection pays a regular monthly income, usually 50–70% of your gross salary, if you are unable to work due to illness or injury. Unlike critical illness cover, it is not limited to a specific list of conditions: it covers any illness or injury that prevents you from working.
The Survival Gap – and Why It Matters More Than Ever
Cover is far more affordable than most people expect. Policies can often be determined solely by the answers in your application form, without a medical examination. And the earlier you arrange cover, the lower your premiums will be. Don’t be part of the 70% who have never considered their protection options. Speak to us today for a personalised review of your life insurance, critical illness and income protection needs. It takes less than an hour and could make all the difference when it matters most.
If you run your own business, the stakes are even higher – there is no employer sick pay to fall back on. But there are also significant tax advantages available to you. Relevant Life Insurance, Executive Income Protection and Key Person Insurance are all company-friendly products that could save you substantial sums while delivering vital protection.
Arrange a free no-obligation consultation with our expert mortgage advisors. We’ll search the whole of market to find the best deal for your circumstances.
Rated 5/5 Stars from 80+ Reviews
We make the complete mortgage process as seamless and trouble-free as possible.
Can’t find what you’re looking for? Get in touch and we’ll be happy to help.
Call us on 01484 817224
Put simply, the more deposit you have, the better, as a higher deposit will generally attract a lower mortgage rate. But, because mortgage products change all the time, do give us a call, as the percentage deposit you need will vary.
Mortgage lenders will have a maximum LTV (loan to value) that they’re prepared to offer you. For example, if you’re looking at a property with a value of £250,000 and the lender offers you £212,500, this means your LTV is 85%, so your deposit would be £37,500 which equates to 15%.
When buying a property, or re-mortgaging, rather than take your word for it, the lender will need a valuation of your intended property purchase, to ensure that what you’re asking to borrow, coincides with the property’s value. In fact, they’ll insist upon it.
It’s well worth investing in a survey too. This will tell you about the general condition of the property. If you’re investing in a property that’s older, or in a general state of disrepair, it would be well worth investing a little extra in a structural survey.
When saving for your deposit, don’t forget to save extra for things like solicitor fees, surveys, stamp duty, home insurance, removal costs, mortgage arrangement fees, etc.
To assess whether or not you can afford a mortgage, lenders will look in detail at things like your salary, any other income you receive. Plus, they will also need to know about any other outgoings such as car loans, credit card debt, personal loans, utility bills, childcare, general living costs. All this is taken into consideration when applying for a mortgage.
Also, be aware that lenders will look at your credit score too. They need to be confident that you can pay back your mortgage and that you pay back any other credit, essentially to make sure that you are a reliable borrower.
We’ve been in the property industry for a number of years now and as such, only work with trusted partners, such as conveyancing solicitors, etc. So if you need help, then do not hesitate to ask and we will put you in touch.
Comparison sites serve their purpose, but, because they don’t have access to the whole of market, the results you will see will be limited. Comparison sites will only show the results of the lenders who have paid to advertise on their site.
At Steeples Mortgages, we’re more than happy to chat things through with you, we much prefer the personal touch, be that by telephone, Zoom or in person.
No matter where you are on your property journey, we have the expertise to find the right deal for you.
Steeples Mortgages is a trusted and respected independent mortgage and financial solutions business based from our high-street office in Brighouse, West Yorkshire. We’ve built our reputation on friendly, client-focused, transparent advice.
As a member of The Equity Release Council and certified in Mortgage Advice and Practice, Steeples Mortgages is all about doing the right thing. We want each and every client to be a lifelong client and as such, we provide the very best customer service, coupled with the most suitable advice all underpinned by honesty, integrity and trust.
A dedicated team committed to giving you the best mortgage and protection advice.
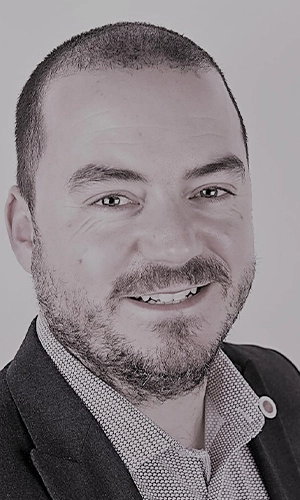
Aaron Steeples
Founder & Managing Director
Founded Steeples Mortgages in 2017. Two decades in finance with a client-first approach built on honest, transparent advice.
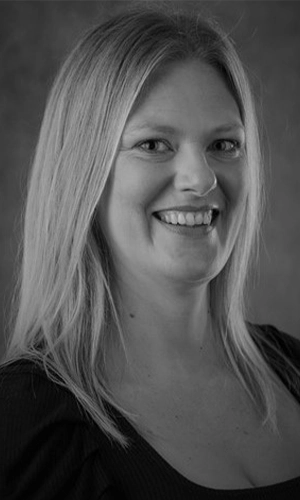
Kylie Waite
Client Completion & Office Manager
Oversees every client’s journey from application to completion, ensuring a smooth and stress-free experience.
Duncan Schofield
Mortgage & Protection Advisor
40 years in financial services. Specialist knowledge with self-employed clients and complex mortgage cases.

Adnan Ahmed
Mortgage & Protection Advisor
Dedicated to helping clients find the right products with clarity and care, from first-time buyers to remortgages.
Cheryl Whitehead
Mortgage Administrator
Cheryl has been working in the mortgage industry for over three years now and has built up valuable experience.