

Residential Mortgages
Access the whole of the UK's panel of lenders. We align you to the best product for your individual circumstances.
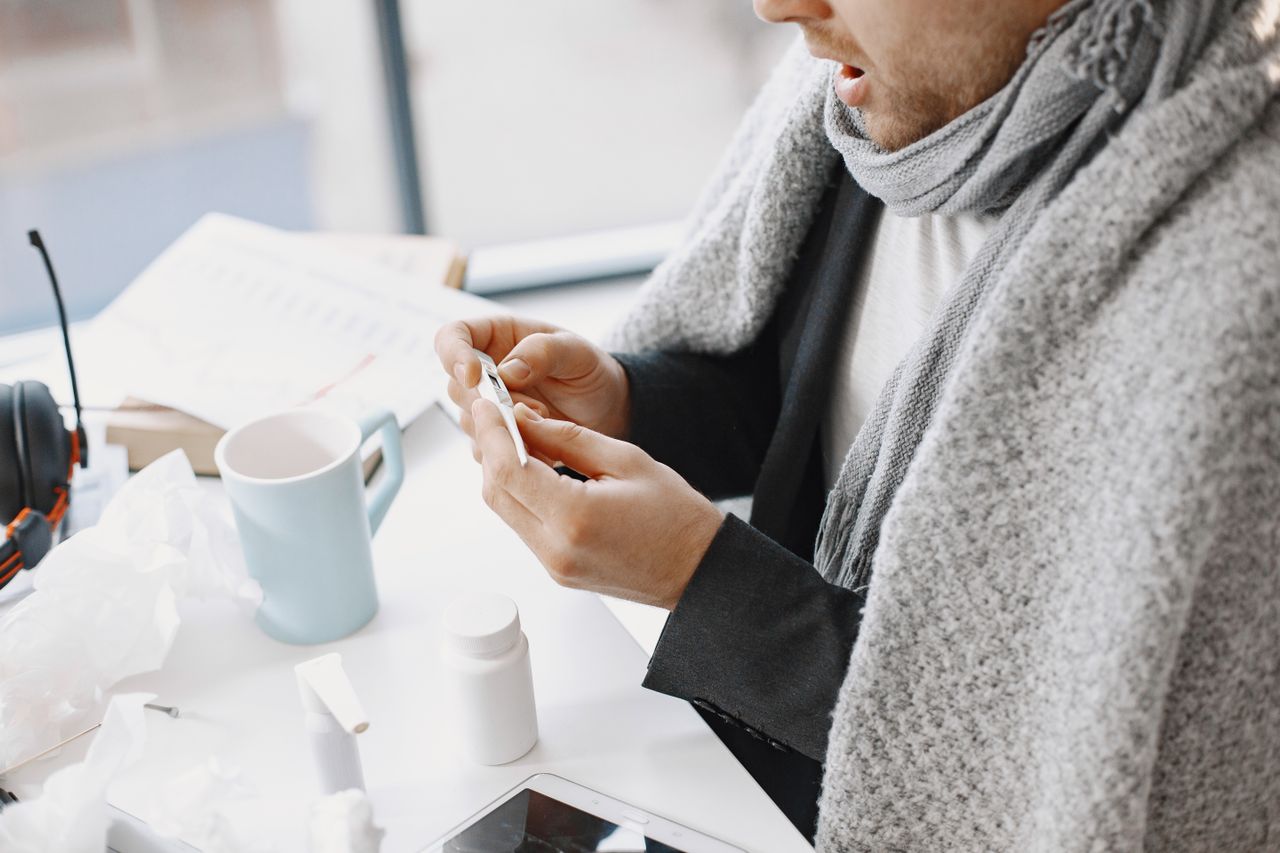
If you couldn’t work because of illness or injury, how long could you keep paying your mortgage and household bills?
It’s a question that’s easy to put off. But with the rules around Statutory Sick Pay changing this year, it’s a good time to think about what financial support you would have if your income suddenly stopped.
Since 6 April 2026, Statutory Sick Pay (SSP) has been available to eligible employees regardless of how much they earn, and it is now payable from the first full day of sickness absence rather than after a waiting period. (Source: GOV.UK, Statutory Sick Pay guidance, updated April 2026.)
The weekly rate for 2026/27 is £123.25, or 80% of average weekly earnings, whichever is lower. SSP can be paid for up to 28 weeks.
The changes mean more people can qualify for support and receive it sooner. But for many households, there’s still a substantial gap between statutory sick pay and their usual income.
Think about your regular commitments: mortgage or rent, energy bills, food, childcare, transport, insurance and other household costs.
For someone earning a typical full-time salary, £123.25 a week represents a significant drop in income. Even if your employer offers enhanced sick pay, it’s worth checking how long it lasts and what happens once it ends.
This is where income protection can play a role.
Income protection is designed to provide a regular income if you are unable to work because of illness or injury, subject to the policy terms and any waiting period. It can be particularly worth considering if you have a mortgage, limited savings, dependants or an income that your household relies heavily on.
One of the most useful things you can do is check your existing safety net.
Ask yourself:
There isn’t a single right answer. For some people, savings and generous employer benefits may provide sufficient protection. For others, income protection could provide an important additional layer of financial security.
If you’re not sure how you would manage financially if illness or injury stopped you working, we’re happy to help. Get in touch, and we can talk through your circumstances, what protection you already have and whether income protection could be worth considering.
Arrange a free no-obligation consultation with our expert mortgage advisors. We’ll search the whole of market to find the best deal for your circumstances.
Rated 5/5 Stars from 80+ Reviews
We make the complete mortgage process as seamless and trouble-free as possible.
Can’t find what you’re looking for? Get in touch and we’ll be happy to help.
Call us on 01484 817224
Put simply, the more deposit you have, the better, as a higher deposit will generally attract a lower mortgage rate. But, because mortgage products change all the time, do give us a call, as the percentage deposit you need will vary.
Mortgage lenders will have a maximum LTV (loan to value) that they’re prepared to offer you. For example, if you’re looking at a property with a value of £250,000 and the lender offers you £212,500, this means your LTV is 85%, so your deposit would be £37,500 which equates to 15%.
When buying a property, or re-mortgaging, rather than take your word for it, the lender will need a valuation of your intended property purchase, to ensure that what you’re asking to borrow, coincides with the property’s value. In fact, they’ll insist upon it.
It’s well worth investing in a survey too. This will tell you about the general condition of the property. If you’re investing in a property that’s older, or in a general state of disrepair, it would be well worth investing a little extra in a structural survey.
When saving for your deposit, don’t forget to save extra for things like solicitor fees, surveys, stamp duty, home insurance, removal costs, mortgage arrangement fees, etc.
To assess whether or not you can afford a mortgage, lenders will look in detail at things like your salary, any other income you receive. Plus, they will also need to know about any other outgoings such as car loans, credit card debt, personal loans, utility bills, childcare, general living costs. All this is taken into consideration when applying for a mortgage.
Also, be aware that lenders will look at your credit score too. They need to be confident that you can pay back your mortgage and that you pay back any other credit, essentially to make sure that you are a reliable borrower.
We’ve been in the property industry for a number of years now and as such, only work with trusted partners, such as conveyancing solicitors, etc. So if you need help, then do not hesitate to ask and we will put you in touch.
Comparison sites serve their purpose, but, because they don’t have access to the whole of market, the results you will see will be limited. Comparison sites will only show the results of the lenders who have paid to advertise on their site.
At Steeples Mortgages, we’re more than happy to chat things through with you, we much prefer the personal touch, be that by telephone, Zoom or in person.
No matter where you are on your property journey, we have the expertise to find the right deal for you.
Steeples Mortgages is a trusted and respected independent mortgage and financial solutions business based from our high-street office in Brighouse, West Yorkshire. We’ve built our reputation on friendly, client-focused, transparent advice.
As a member of The Equity Release Council and certified in Mortgage Advice and Practice, Steeples Mortgages is all about doing the right thing. We want each and every client to be a lifelong client and as such, we provide the very best customer service, coupled with the most suitable advice all underpinned by honesty, integrity and trust.
A dedicated team committed to giving you the best mortgage and protection advice.
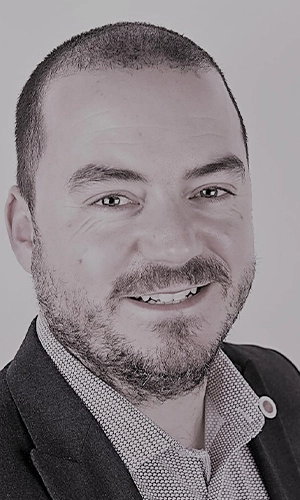
Aaron Steeples
Founder & Managing Director
Founded Steeples Mortgages in 2017. Two decades in finance with a client-first approach built on honest, transparent advice.
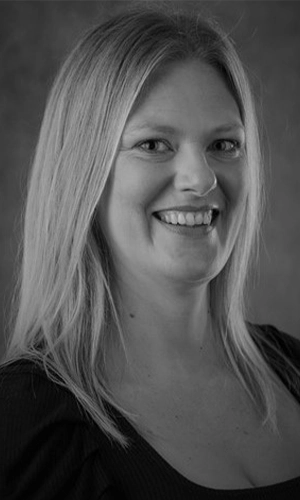
Kylie Waite
Client Completion & Office Manager
Oversees every client’s journey from application to completion, ensuring a smooth and stress-free experience.
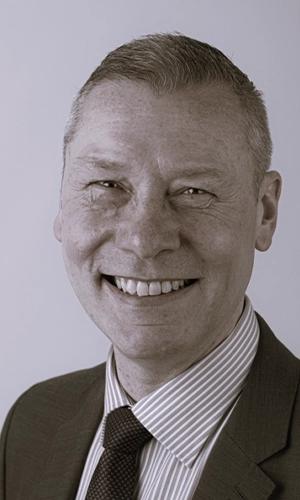
Duncan Schofield
Mortgage & Protection Advisor
40 years in financial services. Specialist knowledge with self-employed clients and complex mortgage cases.

Adnan Ahmed
Mortgage & Protection Advisor
Dedicated to helping clients find the right products with clarity and care, from first-time buyers to remortgages.
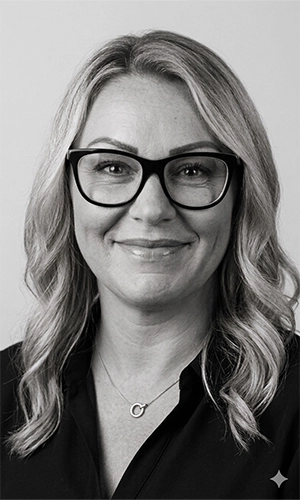
Cheryl Whitehead
Mortgage Administrator
Cheryl has been working in the mortgage industry for over three years now and has built up valuable experience.